Blog
Hard Money Loans 2026: Rates & Trends
Real Estate Investing, Hard Money Loans, 2026 Market Updates
Hard Money Loans in 2026: Rates, Requirements, Trends, and What Borrowers Should Know
Hard money loans—now more often called private or residential transition loans (RTLs)—remain a critical financing tool for real estate investors in 2026. This guide explains how the market has evolved, what’s changed this year, and how borrowers can navigate today’s rates, requirements, and risks with confidence.
Suggested SEO Title: Hard Money Loans 2026: Rates, Requirements, Trends & Risks Explained
Suggested Meta Description: Learn how hard money loans work in 2026, including current rates, requirements, trends, and risks for real estate investors and house flippers.
Suggested URL Slug: hard-money-loans-2026
Quick Answer: What’s Going On With Hard Money Loans in 2026?
In 2026, the hard money (private/RTL) lending market in the United States is large, competitive, and increasingly institutional. Rates have eased from their 2023–2024 peaks but remain significantly higher than conventional mortgages. Typical coupons fall roughly in the 8.5%–11.5% range for experienced borrowers, with an average around 10–10.5% based on recent indices and lender data (Hard Money Rate Index; Baseline Software, 2026). Underwriting has tightened modestly, but deals with strong collateral and clear exit strategies still close quickly—often in days, not weeks.
What Are Hard Money Loans (Now Often Called RTLs or Private Loans)?
A hard money loan is a short-term, asset-based real estate loan primarily secured by the value of the property rather than the borrower’s income or credit profile. In 2026, industry groups and institutional investors increasingly use terms like residential transition loans (RTLs), private lending, or bridge lending instead of “hard money,” reflecting the market’s growing professionalism (How Housing Matters / Urban Institute; Wikipedia – Commercial hard money).
These loans are commonly used for:
Fix-and-flip projects where investors buy, renovate, and quickly resell properties.
Bridge financing between purchase and longer-term take-out financing (such as DSCR or conventional loans).
Ground-up construction for small builders and infill projects that banks consider too small or complex.
Loan terms are typically 6–24 months, with higher interest rates and fees than traditional mortgages, but much faster approvals and closings. Repayment usually comes from selling the property or refinancing into cheaper, longer-term debt—this is known as the exit strategy.
💡 Plain-English definition: A hard money loan is a short-term real estate loan where the lender mainly cares about the property’s value and your plan to pay the loan back, not your W‑2 or tax returns.
The Hard Money Lending Market in 2026: Scale and Direction
The private/RTL market is now a mainstream part of U.S. housing finance. According to data compiled by HardMoneyFacts, more than $85 billion in residential transition loans were originated in 2025, including:
Over $35 billion in fix-and-flip loans
Over $25 billion in ground-up construction financing
Over $25 billion in bridge-only loans
For context, banks held about $91 billion in single-family construction loans, meaning private lenders nearly matched banks in this niche segment (HardMoneyFacts, 2026).
Securitization—the bundling of private loans into bond-like investments—remains an important capital source, but rating agency KBRA projects a flat-to-down RTL securitization market in 2026, with volume forecast around $4.8 billion versus $5.5 billion in 2025 (HardMoneyFacts summarizing KBRA).
📌 Key takeaway: Hard money/private lending is no longer fringe. It’s a multi‑billion‑dollar industry competing directly with banks for certain real estate projects.
What’s Changing in Hard Money Lending in 2026?
1. Rates Have Eased but Remain Elevated
After the rapid rate hikes of 2022–2023, private lending coupons climbed into the low-to-mid double digits. By 2026, competition and stabilizing benchmark rates have brought averages down somewhat:
Period / Source | Typical Rate Range | Notes |
|---|---|---|
Q2 2026 (premier borrowers) | 8.5% – 11.25% | Baseline Software market review (2026) |
Feb 2026 (Hard Money Rate Index) | Median < 10% | RTL coupons typically 9.5% – 11.5%, avg ≈10.5% |
Q3 2026 (Lightning Docs data) | Average 10.32% | Average loan size ≈ $568,390 (PrivateLenderLink) |
Earlier educational sources like NerdWallet, Investopedia, and Forbes describe general hard money ranges of 7%–15% as of 2023 (NerdWallet; Investopedia; Forbes Advisor). The 2026 data suggests current pricing often clusters toward the middle or upper half of that band, depending on risk.
2. Underwriting and Requirements Have Quietly Tightened
Performance data from rated RTL securitizations shows about 5.9% serious delinquencies by month 22, but cumulative net losses below 0.1% thanks to conservative leverage and strong collateral (HardMoneyFacts, 2026). To preserve that track record, many lenders in 2025–2026:
Reduced maximum loan-to-value (LTV) or tightened loan-to-cost (LTC) limits on riskier deals.
Scrutinized exit strategies more closely (for example, realistic refinance assumptions and days-on-market for flips).
Paid more attention to borrower experience and track records, especially on construction and heavy rehab.
While policies vary widely by lender, the broad trend is toward slightly more conservative underwriting than in the “easy money” years, without shutting out solid projects.
3. Competitive Pressure and Institutional Capital
According to the American Association of Private Lenders (AAPL), among the top 100 private lenders, 58 grew in recent periods (average +51% growth), while 41 shrank (average –23%), showing a market where well-run platforms gain share while others contract (AAPL, 2026). Institutional investors and securitizations continue to bring cheaper capital—but also demand better data, documentation, and compliance (NPLA).
📌 For borrowers: This competition can mean sharper pricing and more product options—but also more paperwork and stricter deal screening.
Hard Money Loan Interest Rates and Fees in 2026
Hard money loan rates in 2026 are shaped by: Federal Reserve policy, investor yield expectations, property risk, leverage, and lender competition. While each lender sets its own pricing, current data supports the following general picture for U.S. investment property loans:
Interest rates: Commonly about 8.5%–11.5% for experienced borrowers on lower-risk deals, with higher rates for heavy rehab, higher LTV, or weaker sponsors (HardMoneyFacts; Baseline Software).
Origination points: Often 1–4 points (1–4% of the loan amount) paid at closing. Some lenders charge more on small or complex projects; others discount points for repeat borrowers. (Ranges consistent with 2023 guidance from NerdWallet and Forbes.)
Other fees: Third‑party appraisal, title, legal, document fees, and sometimes underwriting or processing charges. These vary widely and should be itemized in a Loan Estimate or term sheet.
💡 Pro Tip: When comparing offers, calculate the all‑in cost—interest, points, and fees over the actual time you expect to hold the loan—not just the headline rate.
Hard Money Loan Requirements in 2026: What Lenders Look For
While every lender has its own playbook, most 2026 hard money / RTL programs echo the core requirements described in earlier educational sources like Investopedia and Forbes (Investopedia; Forbes Advisor), with some tightening on leverage and documentation:
Property value & appraisal: A professional appraisal or broker price opinion (BPO) is usually required. Lenders base the loan on as‑is value and/or after‑repair value (ARV) for fix‑and‑flip deals.
LTV and LTC ratios: Many lenders cap investment-property LTV around 60%–75%, sometimes lower for land or heavy construction. Loan‑to‑cost (LTC) limits often sit near 80%–90% of total project cost, requiring the borrower to bring cash or equity.
Down payment / equity: Expect to contribute 20%–30% (or more) of purchase plus rehab from your own funds or subordinated capital. Higher equity usually earns better rates and terms (consistent with 2023 guidance from NerdWallet).
Borrower experience: In 2026, experience is a major differentiator. Repeat investors and builders with a proven record often qualify for higher leverage and faster closings than first‑time flippers.
Exit strategy: Lenders want a clear, realistic plan to repay—usually selling the property or refinancing into a DSCR or conventional loan. They will stress‑test this plan against current market conditions (for example, days on market, rent levels, and refinance rates).
Documentation: Even though underwriting is “asset‑based,” most lenders now collect entity docs, personal ID, bank statements, project budgets, and sometimes credit reports or tax returns, especially when loans are destined for securitization.
Important: Requirements vary significantly by state, property type, and whether the loan is consumer‑purpose or business‑purpose. Do not assume one lender’s terms apply everywhere.
Who Should Consider a Hard Money Loan in 2026?
Hard money loans are not designed for long‑term homeowners. They are best suited for real estate investors and business‑purpose borrowers who:
Need to close quickly on a property (for example, auction purchases, distressed sales, or competitive bidding situations).
Are buying properties that don’t qualify for conventional financing because of condition, title complexity, or income documentation gaps.
Have a short‑term business plan (flip, reposition, or build) that can repay the high‑cost loan within 6–24 months.
On the other hand, borrowers seeking to live in the property long‑term or who can qualify for bank or agency financing will almost always be better served by lower‑cost, longer‑term loans, even if they take more time to close.
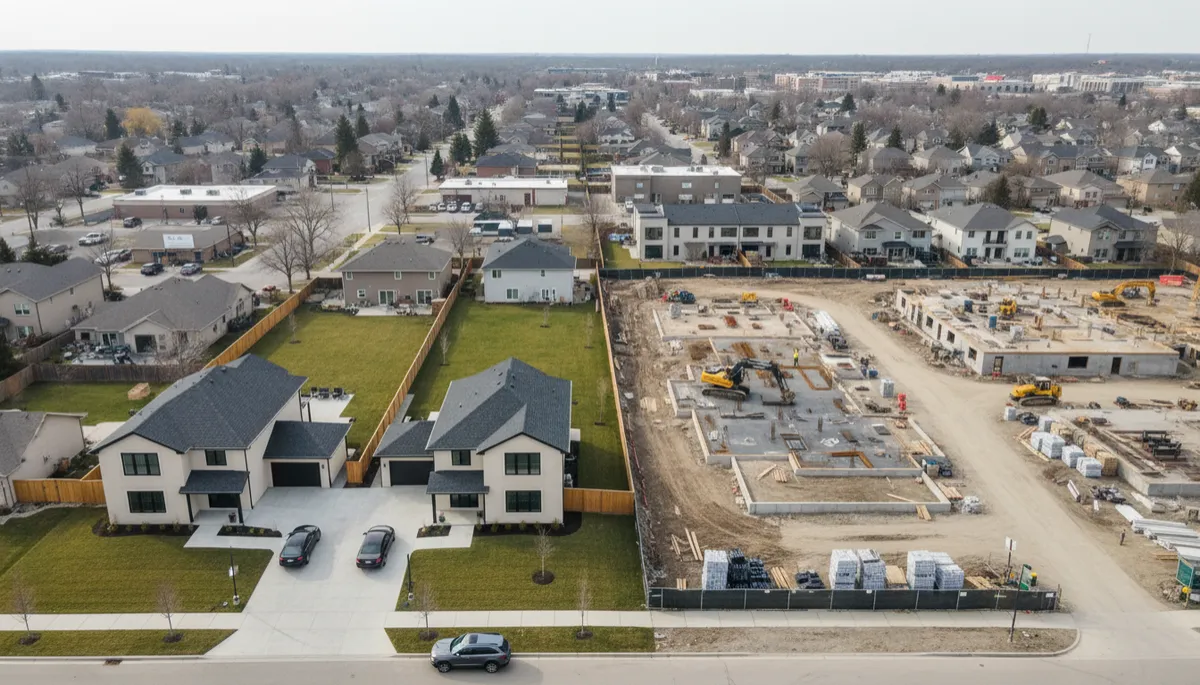
Aerial view of a renovated duplex and a nearby construction site, representing fix-and-flip and...
Private lenders often fund both cosmetic flips and small ground-up projects in 2026.
Hard Money Loans vs. Traditional Mortgages
Feature | Hard Money / RTL | Traditional Mortgage |
|---|---|---|
Typical use | Investment, flips, bridge, construction | Owner‑occupied homes, stabilized rentals |
Speed to close | Often days to a couple of weeks | Often 30–60+ days |
Rate range (2026 typical) | Roughly 8.5%–11.5%+ depending on risk | Generally lower, often mid‑single digits to high single digits depending on product and market |
Term length | Short‑term (6–24 months common) | Long‑term (15–30 years typical) |
Underwriting focus | Property value, project, exit strategy, sponsor experience | Income, credit, debt‑to‑income, property, and long‑term affordability |
Note: These are general patterns, not universal rules. Some banks offer bridge products, and some private lenders offer longer‑term DSCR loans.
Benefits and Risks of Hard Money Loans in 2026
Potential Benefits
Speed: Ability to close quickly and compete with all‑cash buyers on distressed or time‑sensitive deals.
Flexibility: Willingness to fund properties that don’t meet traditional standards (vacant, unfinished, heavy rehab, or unconventional income).
Project‑based underwriting: Focus on deal economics and collateral rather than just personal tax returns.
Major Risks
High carrying cost: Double‑digit interest plus fees can quickly erode profits if projects run long or over budget.
Short maturities: 6–12‑month loans leave little room for market slowdowns, permitting delays, or construction surprises.
Default and foreclosure risk: If you cannot sell, refinance, or pay off the loan at maturity, the lender may charge default interest, extend at a cost, or ultimately foreclose on the property.
Risk management tip: Stress‑test your deal. Ask: “If my project takes 6 months longer and sells for 10% less, do I still have a path to repay this loan?”
Regulatory and Legal Considerations in 2026
There is no single nationwide “hard money law.” Instead, private lenders operate under a patchwork of federal consumer protection rules and state licensing and usury laws. Key points for 2026:
Business‑purpose vs. consumer‑purpose: Many hard money loans are structured as business‑purpose loans to investors, which may be exempt from certain federal consumer protections. However, that does not mean all such loans are unregulated, and mis‑classifying a consumer loan as business‑purpose can create legal risk. The CFPB continues to enforce laws like the Truth in Lending Act (TILA) and related regulations for covered loans (CFPB).
State regulation: Many states require private lenders or brokers to hold specific licenses for certain types of loans or property uses. State regulators (often departments of financial institutions or real estate) may also set maximum rates or fees for certain loan categories. Requirements and limits differ by state and may change over time, so local legal advice is important.
As of late 2026, no single, widely cited federal law has redefined hard money lending across the board. Instead, regulators continue to focus on disclosure, fair dealing, and accurate characterization of loans, particularly where consumers or owner‑occupants are involved. Investors should not assume that every hard money loan is exempt from consumer rules or that high rates are always permissible—state law and loan purpose matter.
Emerging Practices and Technology Shaping Hard Money in 2026
Several structural shifts are reshaping how hard money loans are originated and managed:
Digital underwriting platforms: Many lenders now use integrated LOS (loan origination systems) and data providers to pull title, AVMs, credit, and rent comps quickly—shortening approval timelines and standardizing documentation (Baseline Software).
Institutional credit lines and securitization: Larger platforms rely on warehouse facilities and securitizations, which push them toward more consistent underwriting, clearer disclosures, and stricter collateral guidelines (NPLA).
Focus on speed and certainty of close: Industry commentary notes that investors often choose the lender that can close fastest with reliable execution, even if another lender offers slightly cheaper rates (Baseline Software).
Borrower implication: Well‑organized investors with complete documentation and clear project budgets often secure the best terms because they help lenders underwrite efficiently.
How to Choose a Hard Money Lender in 2026
Check licensing and compliance: Verify that the lender or broker is properly licensed where required for your type of loan and property. State regulator websites often provide searchable license databases.
Demand transparent terms: Ask for a written term sheet outlining rate, points, fees, prepayment penalties, extension options, default interest, and maturity date. Avoid lenders unwilling to put key terms in writing early in the process.
Evaluate speed and track record: Talk to other investors, read reviews, and ask how often they close on time. In a competitive 2026 market, certainty of close can be worth more than a quarter‑point in rate.
Match lender to your strategy: Some lenders specialize in fix‑and‑flip, others in DSCR or small balance multifamily, and others in ground‑up construction. Choose a lender that regularly funds your type of deal in your market.
Internal linking idea: On your site, link this section to detailed guides on “how to vet a private lender,” “fix‑and‑flip financing,” and “DSCR loan basics.”
How to Apply for a Hard Money Loan: Step‑by‑Step
Define your project and exit strategy. Are you flipping, building, or holding as a rental? How will you repay the loan—sale, refinance, or something else?
Prepare a basic deal package. Include purchase contract, photos, a rehab or construction budget, timeline, and your experience summary. The clearer your plan, the easier underwriting becomes.
Request quotes from multiple lenders. Compare rate, points, fees, leverage, draw schedules, and closing timelines—not just a single headline number.
Complete the application and provide documentation. Expect to share ID, entity docs, bank statements, insurance information, and possibly credit authorization or tax returns, depending on the lender’s model and funding source.
Review the loan documents carefully. Pay attention to default triggers, extension options, personal guarantees, and any prepayment penalties. Consider having a real estate attorney review the documents, especially on large or complex deals.
Hard Money Lending Outlook for the Rest of 2026
Available 2026 outlooks suggest a market that is maturing rather than exploding. KBRA expects slightly higher default rates in private credit overall (around 2% in 2026 vs. 1.5% in 2025) as platforms manage slower deal flow and capital deployment challenges (KBRA Private Credit Outlook 2026). At the same time, AAPL data shows many lenders still growing meaningfully, particularly in DSCR and stable bridge segments (AAPL).
Forecasts are inherently uncertain, but the consensus appears to be:
Stable‑to‑slightly lower rates if broader interest rate pressures ease, but still above bank financing.
Continued competition on speed and service rather than dramatic price cuts.
Ongoing institutionalization of the space, favoring lenders with strong compliance, data, and risk management.
Investor implication: Well‑underwritten deals with conservative leverage and realistic timelines remain financeable. Marginal projects with thin spreads or speculative assumptions may struggle to find capital.
Frequently Asked Questions About Hard Money Loans in 2026
1. Are hard money loans more expensive in 2026 than before?
Compared with the ultra‑low‑rate environment before 2022, yes—rates are higher. But compared with the peak stress years of 2023–2024, 2026 hard money rates have moderated into roughly the mid‑to‑high single digits above risk‑free benchmarks, often around 8.5%–11.5% for strong borrowers, according to market indices and lender data cited above.
2. What LTV can I expect on a hard money loan in 2026?
Many lenders still target 60%–75% LTV on investment properties, sometimes lower for land or heavy construction, and sometimes higher for low‑risk, repeat borrowers. LTC limits often sit around 80%–90% of total project cost. These are common ranges, not guarantees—each lender sets its own maximums.
3. Do I need good credit to get a hard money loan?
Hard money is more flexible than bank financing, but credit still matters—especially in 2026 as lenders compete for institutional capital. Many lenders will review your credit report even if they emphasize the property and project. Strong credit can help with pricing and leverage, but investors with past issues may still qualify if the deal and collateral are compelling.
4. Are hard money loans regulated?
Yes—just not under a single nationwide statute. Business‑purpose investment loans may be exempt from some consumer rules, but federal laws (such as TILA for covered loans) and state licensing, disclosure, and usury laws still apply in many situations. Always confirm with counsel or a knowledgeable compliance professional how your specific loan will be treated in your state.
5. Can I use a hard money loan to buy my primary residence?
Some private lenders will not lend on owner‑occupied homes at all because of additional consumer protection rules and licensing requirements. Others may offer specialized products that comply with those rules. In general, hard money is most common for non‑owner‑occupied investment properties. If you plan to live in the property, talk with a lender and a legal professional about applicable regulations in your state.
6. What happens if I can’t pay off the hard money loan on time?
Your options depend on your loan documents and state law. Many lenders may offer a paid extension if the project is close to completion. If no solution is reached, the lender can charge default interest, pursue legal remedies, and potentially foreclose on the property. This is why it’s critical to build conservative timelines and backup exit strategies into your business plan.
Conclusion: How Borrowers Can Navigate Hard Money Loans in 2026
The 2026 hard money—now “private lending” or “RTL”—market is deep, data‑driven, and highly competitive. Rates have settled from their peaks but remain meaningfully higher than bank financing. Underwriting has tightened just enough to reward prepared investors with solid deals and clear exit strategies, while marginal projects face more scrutiny.
For real estate investors, the message is clear: treat hard money as a professional tool, not a last‑ditch rescue. Build conservative budgets, allow extra time, stress‑test your exit, and work with lenders who are transparent about pricing, timelines, and expectations. Before you sign, consider speaking with a qualified real estate attorney or financial advisor to understand how the loan fits into your broader investment strategy and risk tolerance.
If you publish this article on your site, consider linking readers to deeper resources on DSCR loans, fix‑and‑flip project planning, and real estate risk management so they can turn today’s hard money market into a well‑informed advantage rather than an expensive surprise.

RP Capital Lending is a d.b.a of RP Capital Partners Inc (NMLS # 2469193)
Disclaimer: Loans only apply to non-owner occupied properties. Rates, terms and conditions offered only to qualified borrowers, may vary upon loan product, deal structure, other applicable considerations, and are subject to change at any time without notice.
Copyright © 2026. All Rights Reserved.